Skip to main content Skip to docs navigation
Benchmark IT Solutions
Back to all case studies

Case studyRMD Almanac: Required Minimum Distribution Engine

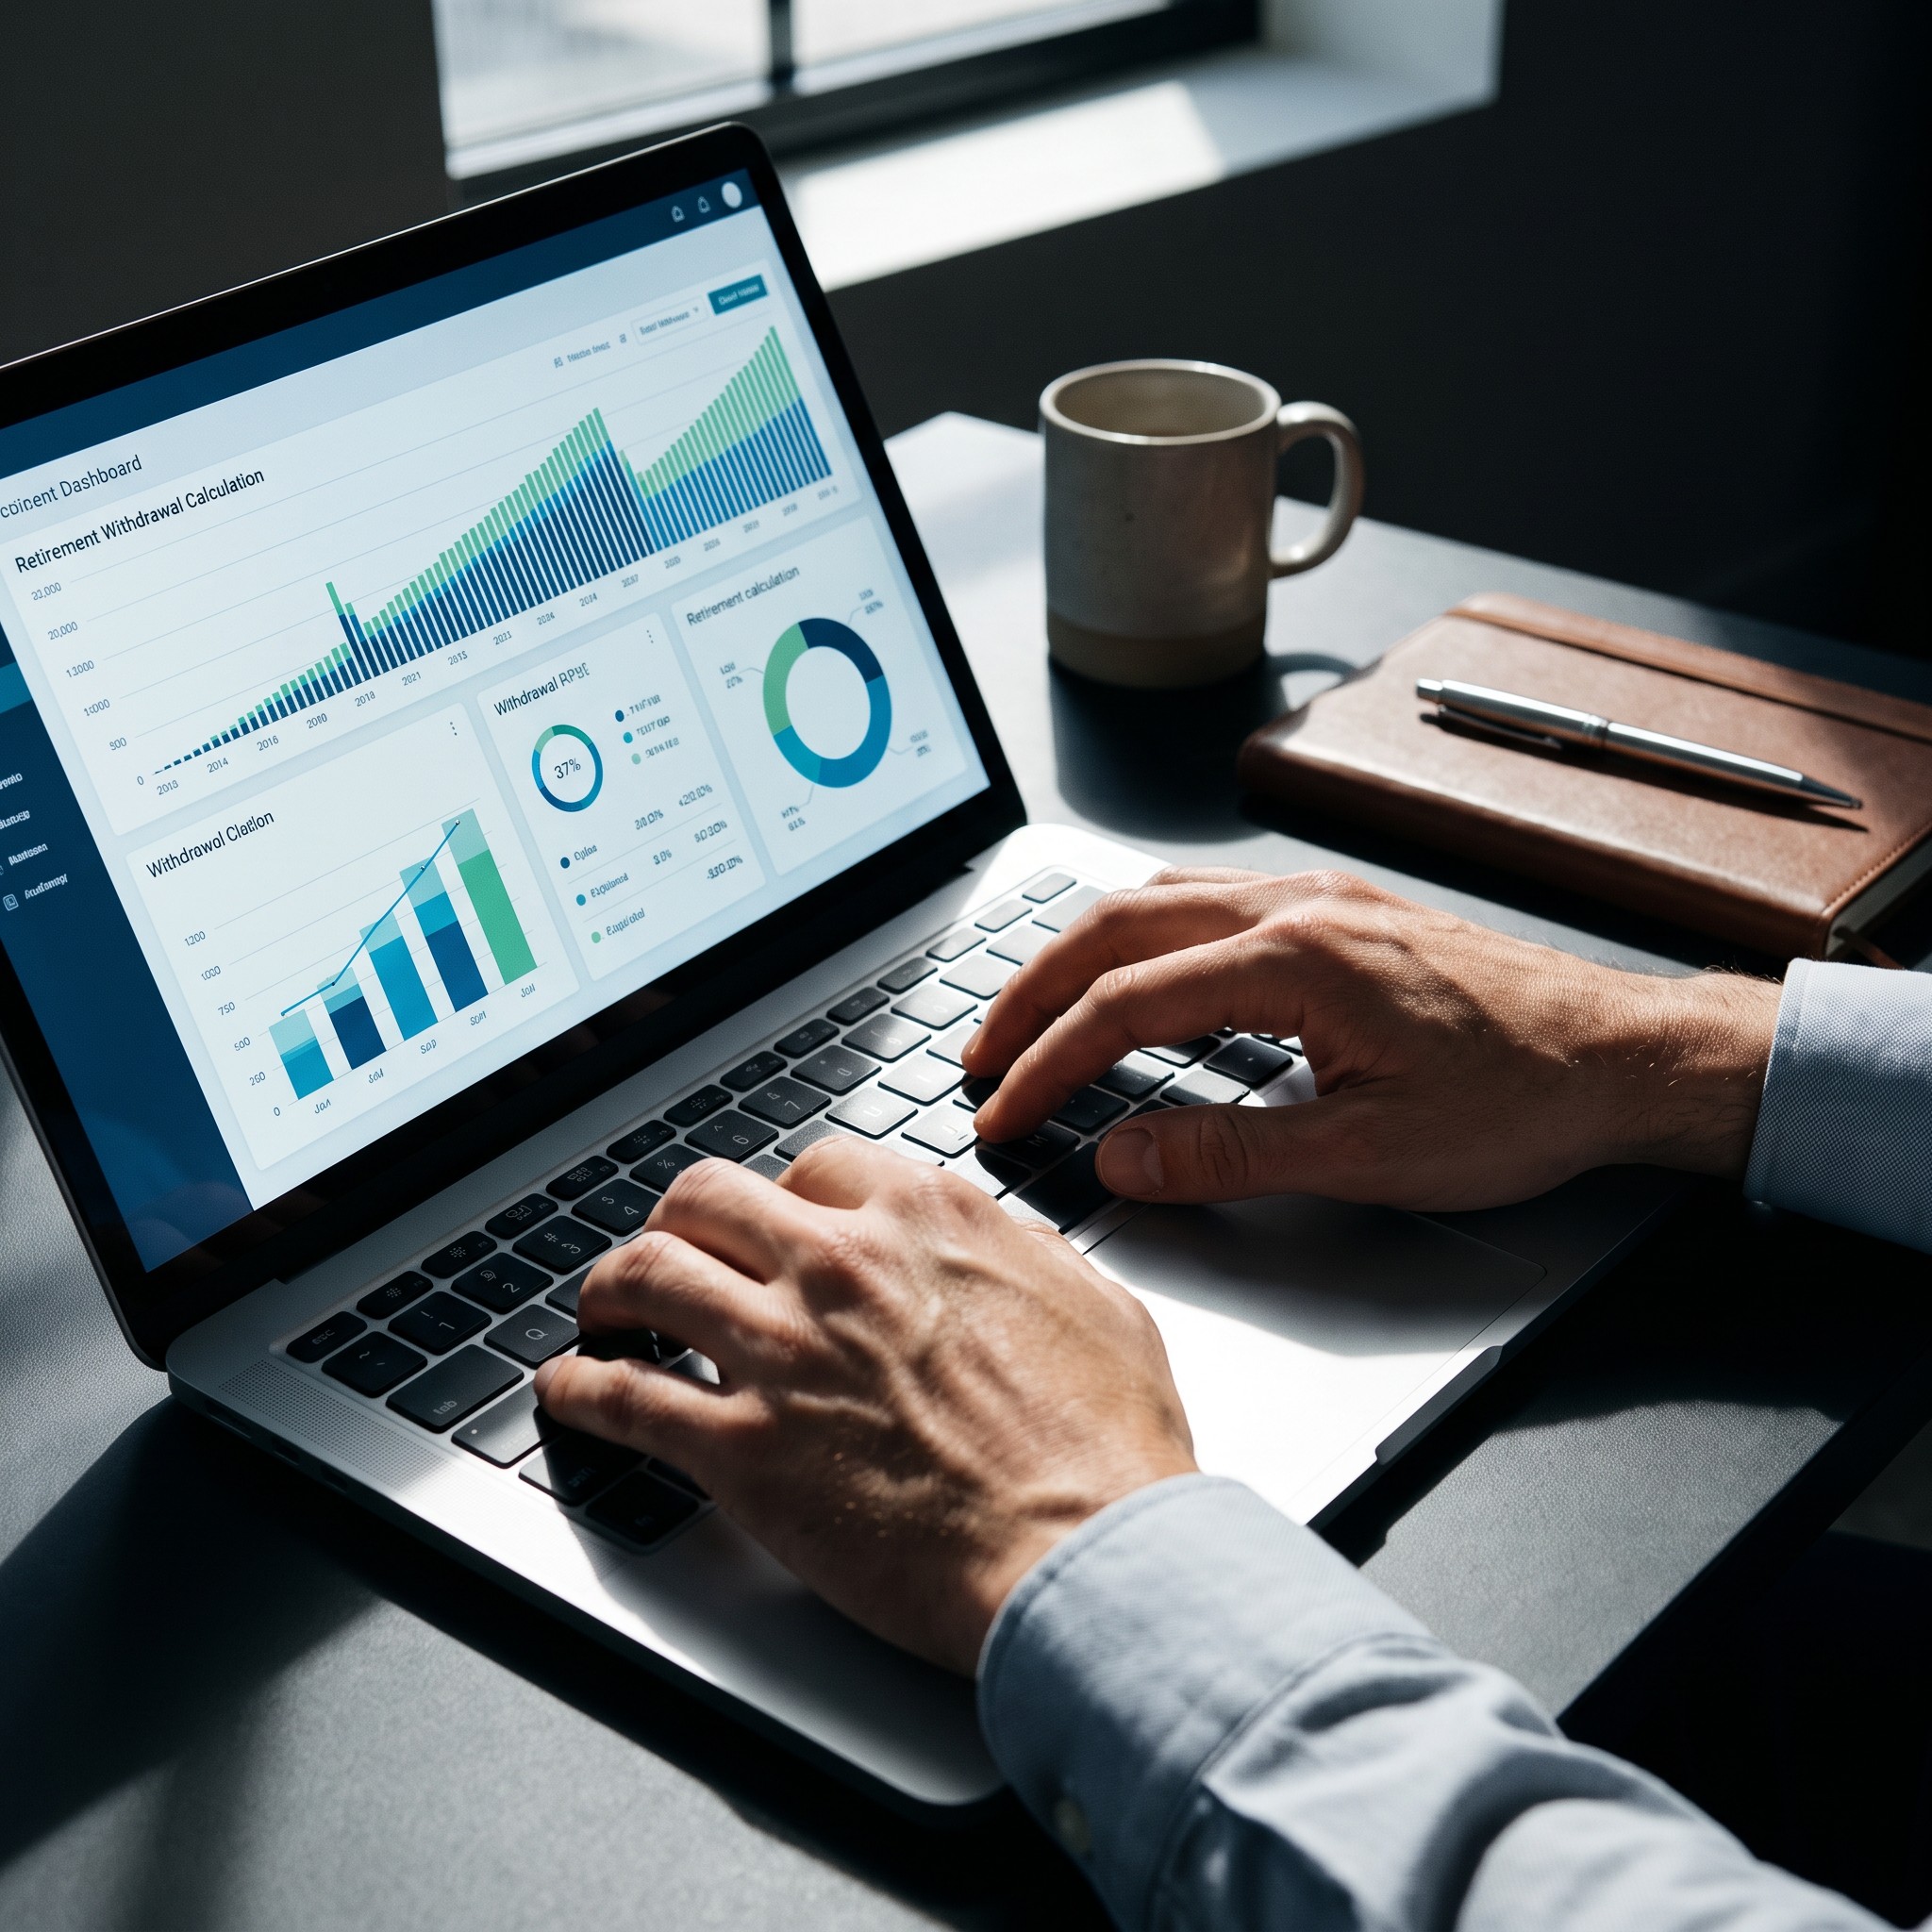
RMD Almanac, Benchmark's Required Minimum Distribution engine, turning a once-a-year IRS compliance chore into an accurate, transparent planning conversation.

Industry
Wealth Management / Retirement Planning
Headquarters
—
RMD Almanac: Required Minimum Distribution Engine
60%
Fewer cases escalated to specialists
Key Metrics Measured after
rollout
0%
Calculations Showing Full IRS Table and Math
0%
Fewer Cases Escalated to Specialists
Background

A wealth management firm replacing hand-calculated RMDs with a rules-aware, auditable engine.

A leading US based wealth management and retirement planning firm serves thousands of clients who hold retirement accounts.

A Required Minimum Distribution, or RMD, is the minimum amount a person must withdraw each year from certain US retirement accounts once they reach the applicable starting age.

It is not optional, and the required amount changes every year as the balance and the owner's age change.

Getting it wrong is expensive: a shortfall can trigger a 25% excise tax, reduced to 10% when corrected within the applicable correction period.

The firm's advisors calculated RMDs by hand every year, looking up IRS life expectancy tables and working through spreadsheets, client by client.

The firm's advisors handle a wide mix of situations: standard owned accounts, spousal cases, inherited accounts, and clients with multiple account types.

Each case can point to a different IRS table and a different set of rules, and the hard cases were routinely escalated to a small group of specialists.

For clients, the RMD was a once a year compliance chore with no bigger picture.

The firm wanted a single engine that gets the number right every time, shows the math behind it, and turns the mandatory withdrawal into a planning conversation about where every retirement dollar goes.

Background
Wealth Management / Retirement Planning
—
Challenges faced & defined solution

5 real bottlenecks. 6 matching fixes.

Every operational bottleneck reported was matched to the workstream(s) that resolved it.

The challenge

A Number That Must Be Right Every Year

The required amount changes each year with the balance and the owner's age, and every client needs a fresh, correct answer.

Defined solution

A Clear Eight Step Calculation

The engine confirms an RMD is due, identifies owned or inherited status, selects the applicable IRS table, finds the factor, divides the prior Dec 31 balance by the factor, subtracts distributions already taken, shows the remaining amount and its deadline, and reveals the full math behind the answer.

The challenge

Costly Penalties for Mistakes

A missed or short RMD can trigger a 25% excise tax on the shortfall, reduced to 10% only if corrected within the correction period.

Defined solution

Penalty Exposure Flagged Early

The engine surfaces any shortfall and its excise tax exposure before it hardens into a penalty.

The challenge

Complex IRS Table Selection

Choosing between the Uniform Lifetime, Joint and Last Survivor, and Single Life Expectancy tables depends on age, spouse, and beneficiary details.

Defined solution

Built in IRS Intelligence

The engine knows which rules apply. It selects the right table automatically: Uniform Lifetime for most owned accounts, Joint and Last Survivor when the spouse is the sole beneficiary and more than 10 years younger, and Single Life Expectancy for inherited accounts. It applies the age 73 starting rule, the April 1 first year deferral, and the Roth exception where no distributions are required while the original owner is alive.

The challenge

Hard Cases Beyond Simple Calculators

Multiple accounts, inherited accounts, and missed RMDs involve rules that most calculators cannot handle.

Defined solution

The Hard Cases Handled

Each account's RMD is figured on its own prior year balance. IRA amounts can be aggregated across IRAs, while employer plan RMDs stay separate, so the engine never blindly combines account types. Inherited account logic covers the owner's date of death, the beneficiary type, the required beginning date, and the 5 year or 10 year distribution rules.

The challenge

No Planning View

Clients saw only a mandatory withdrawal, with no picture of what they keep, what goes to tax, and what reaches their heirs over a lifetime.

Defined solution

A Lifetime Planning Canvas

Beyond the yearly number, the engine maps the lifetime destination of the corpus: what the owner keeps, what goes to tax, and what reaches heirs, turning a compliance chore into a planning conversation.

The Impacts

Real, measurable improvements in accuracy, penalty avoidance and advisor capacity.

Right the First Time

Every client received a correct, current year RMD with the table, factor, and full calculation shown.

Penalties Avoided

Shortfalls were flagged before deadlines, so exposure was corrected instead of becoming an excise tax.

Hard Cases Without Specialists

Advisors handled multiple accounts and inherited account cases directly, without escalation.

Transparent Answers

The full balance divided by factor calculation was visible in plain view, building trust with clients and reviewers.

From Chore to Conversation

The lifetime view of owner, tax, and heirs turned the annual RMD into a planning discussion and a reason to engage clients.

Faster RMD Turnaround

Time to produce a complete, documented RMD answer was likely reduced from hours of manual lookup to minutes per client.

Excise Tax Exposure Eliminated

Exposure to the 25% excise tax was likely eliminated by flagging shortfalls before deadlines.

Illustrative Lifetime Planning Example

An illustrative $1M corpus is mapped across a client's lifetime: about $1.75M in lifetime RMDs, $420K to tax, and $396K reaching heirs, giving advisors a clear planning picture.

Ready to take your business on the
path of success?